What Happens If OpenAI Dies?
What Happens If OpenAI Dies?
Author: Ed Zitron (Where’s Your Ed At) URL: https://www.wheresyoured.at/what-happens-if-openai-dies/ One-line: OpenAI has promised more than any company in history can deliver: $800B+ in compute obligations, a 10x revenue ramp, and a raise of $100B or more every year from a shrinking pool of investors. Zitron argues it is now irresponsible not to plan for its collapse, and he sketches what that collapse would look like.
Key claims
- The trigger was one week of news. In the same week OpenAI completed a $7 billion internal share buyback, COO (and former CFO) Brad Lightcap and Chief Revenue Officer Denise Dresser both left. Dresser had been there eight months and likely gave up unvested stock. Four months earlier she had told CNBC she had “never seen this level of conviction.”
- Anthropic going public first would hurt OpenAI. Investors told the FT that Anthropic would be worth $2 trillion with $100–120B in annualized revenue by the end of 2026. Reuters reported that Wall Street values it on revenue two years out ($190–200B). If Anthropic’s IPO exposes its “horrifying economics,” Zitron cannot see how OpenAI follows, given it “lost $20.9 billion in 2025 on $13.07 billion in revenue.”
- “Annualized revenue” is a marketing number. OpenAI multiplies its last four weeks by 12, and a source told The Information that using the peak week instead would show ~$30B. It took OpenAI until mid-August to be “on track” for a $40B run rate, $7B below Anthropic’s run rate in May and $25B below Anthropic’s at the end of July. In Q1 2026, OpenAI spent $12.1B on cost of revenue and training against $5.7B in revenue, before sales and marketing ($5.73B in 2025). “The more money OpenAI makes, the more its services cost.”
- The obligations exceed $800B, and $147B of it comes due by the end of 2027. The WSJ reported $750B in projected compute spend through 2030. Analyst notes (Wells Fargo, UBS, Barclays) estimate OpenAI will account for $126B+ of Google, Amazon and Microsoft cloud revenue in the next 18 months, and about $20B of Oracle’s. On top of that: ~$87.5B in Broadcom chips, a $22.4B CoreWeave deal, $20B with Cerebras, a theoretical $30B Georgia project, a consumer device, data and salaries.
- The projections require a 10x revenue ramp. The Information’s figures show $284B in revenue by 2030, more than NVIDIA’s FY2026 ($215.9B), and a swing from −$51B free cash flow in 2029 to +$39B in 2030. Zitron’s two possible outcomes: OpenAI becomes “the literal largest and most-successful company of all time,” or it runs out of money.
- The pool of investors is drying up. $110B of the last $122B round came from Amazon ($50B), NVIDIA ($30B) and SoftBank ($30B), leaving $12B from everyone else, which Zitron says “isn’t enough to cover a single quarter’s compute costs.” SoftBank owes $10B on October 1, 2026 and has borrowed against its whole OpenAI stake. Amazon’s and Google’s free cash flow has turned negative. Jensen Huang has said NVIDIA’s $30B is likely its last, and NVIDIA’s “backstop” of a 10GW Ohio site covers asset value up to $105B, not OpenAI’s lease payments.
- The valuation is stuck. The round valued OpenAI at $852B, and per the NYT, Altman treated anything below a $1 trillion IPO as a “nonstarter.” That leaves a later investor about a 15% premium for “the single-most-important startup since Google or Facebook.” Thrive’s 2022 growth fund has returned 0.3x, which Bloomberg says puts it above the top 5% of funds, with much of it tied up in OpenAI.
- Three ways it could die. (1) Microsoft absorbs OpenAI: it cancels the other clouds’ contracts, restates the $250B “incremental Azure spend,” and strips back free ChatGPT. (2) OpenAI is allowed to fail: nearly a trillion dollars of contracts go unpaid, CoreWeave and Cerebras collapse, customers are moved to Foundry, Bedrock and Vertex, and Altman becomes the scapegoat, though Zitron says “the person to blame is Satya Nadella.” (3) It merges with Anthropic into a $2T+ entity that “would be ruinous for everybody involved.” Signs to watch: falling run rates, lower OpenRouter burn, price cuts, sagging CoreWeave cash flow (OpenAI pays Net 360), Cerebras revenue (50–70% from OpenAI), and changes in hyperscaler guidance.
Notable quotes
“I just have never seen this level of conviction spread so quickly and consistently within the industries.” — Denise Dresser to CNBC, April 2026
“OpenAI calculates annualized revenue by multiplying the last four weeks’ revenue by 12. If OpenAI calculated the metric based on revenue spikes just in the last week, OpenAI’s annualized revenue would be roughly $30 billion, one of the people said.” — The Information
“Could, could, could, could, could, could could COULD! It’s always a bloody could or will or might with these fucking companies.”
“OpenAI’s advisers presented company executives with the option of waiting until 2027 to go public with a $1 trillion valuation, or lower the targeted valuation for a quicker I.P.O. Mr. Altman, said one person in contact with him on the topic, responded that any change to the trillion-dollar valuation was a nonstarter.” — The New York Times
“So, there’re really only two eventualities: OpenAI becomes the literal largest and most-successful company of all time. OpenAI runs out of money at some point.”
“And at some point, OpenAI will simply not be able to pay its bills, or more precisely, it will have to hand over money to somebody who will not accept equity or IOUs in return.”
“OpenAI doesn’t have to be illegal to be dangerous.”
Charts and figures
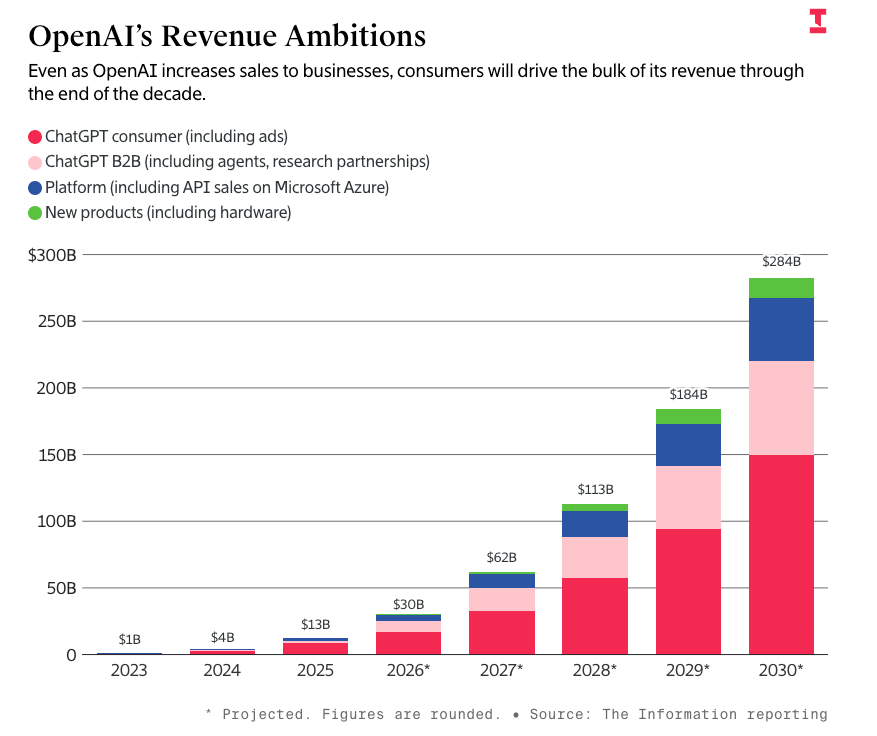
The 10x revenue ramp Zitron calls “a magical mystery tour through revenue hallucinations.” It nearly triples 2025 revenue, doubles 2026, nearly doubles 2027, then grows 68% and 64%.
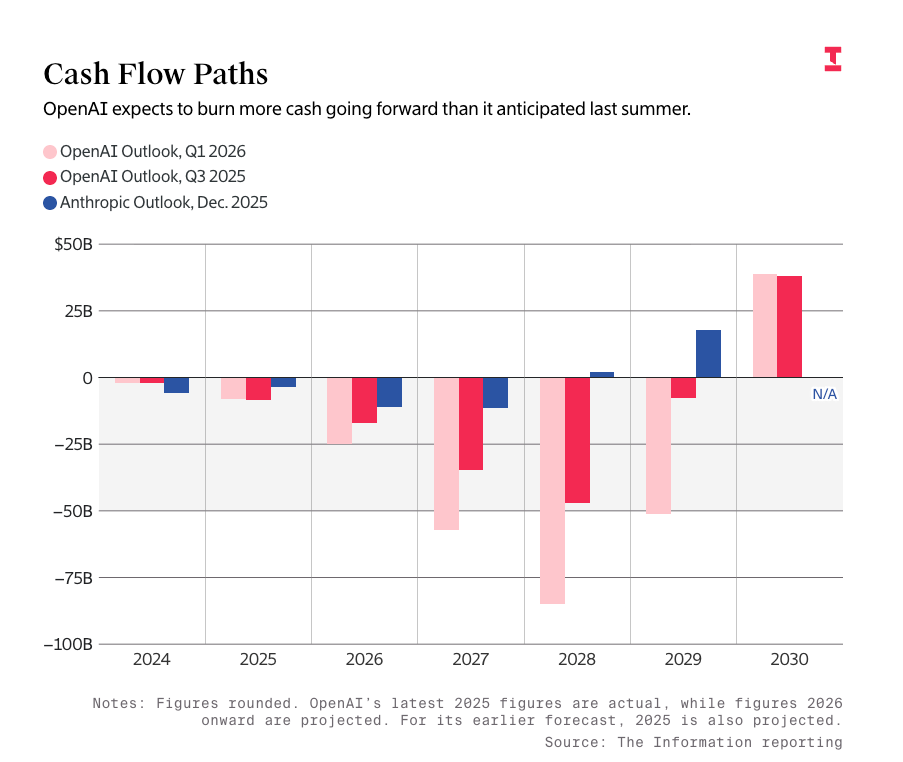
The chart Zitron shares to show the projected swing from −$51B free cash flow in 2029 to +$39B in 2030.
How it connects
- Ed Zitron is the author. He notes he has been writing about OpenAI’s instability since November 2023, and admits he “might have underestimated its staying power.”
- OpenAI: the subject. The piece covers its revenue, burn, obligations, every funding round since October 2024, and three possible endings.
- Sam Altman: refused to IPO below $1 trillion, told Brad Gerstner OpenAI would make “well more than $13 billion” in 2025 (it made $13.07B), and is the likely scapegoat if OpenAI fails.
- Microsoft and Satya Nadella: OpenAI is 70% of Microsoft’s AI revenue, so Microsoft is the most likely acquirer. Zitron argues Nadella, who “made the initial investment, bought all the GPUs,” is the one really to blame.
- Anthropic: OpenAI’s only real competitor, with a faster-growing run rate and an earlier IPO push. Its own $300B+ in commitments mean the same critique applies to it.
- NVIDIA and Jensen Huang: $30B in the last round, an asset-value backstop on the Ohio site rather than a payment guarantee, and the “$500 billion” financing figure Bloomberg reported was announced before the deals came together.
- SoftBank: $30B in, a loan against its whole OpenAI stake, $10B due October 1, 2026. Zitron calls its collapse “a very real possibility.”
- Amazon and AWS: sent the remaining $35B of its $50B (reportedly conditional on an IPO or AGI) while its own free cash flow went negative. About $9B of OpenAI’s compute runs through AWS. Andy Jassy appears among the executives who would blame Altman.
- Google and Sundar Pichai: UBS estimates OpenAI will spend $9.375B on Google Cloud in 2026 and $12.5B in 2027. Google is a possible investor, but its free cash flow is negative too.
- Oracle: an estimated ~$20B in OpenAI revenue. Zitron says “Oracle will collapse without OpenAI’s revenue.”
- CoreWeave: a $22.4B five-year deal, and the place to watch, since OpenAI pays on Net 360 terms.
- Thrive Capital: its 2022 growth fund returning 0.3x, with OpenAI as its largest bet, is Zitron’s example of LPs’ patience running out.
- Gavin Baker: mentioned as the booster who expects OpenAI and Anthropic to become “the only companies” in the world.
- Blackstone and BlackRock: private-credit funds already in OpenAI’s rounds. Zitron doubts they can carry $100B+ a year when they are struggling to fund data centers.
- Ramp: its data shows customers were slow to adopt Anthropic’s pricier Fable model, Zitron’s evidence that AI prices can’t go up.
- Venture Capital: OpenAI and Anthropic have never raised more than $30B at a time from VCs, and Anthropic’s rounds needed 28 to 37+ investors. Zitron reads that as a sign of how hard the capital is to mobilize.
- Artificial Intelligence and AI Industry: OpenAI is “the majority of compute demand across effectively every provider” and “at least 20% of hyperscaler cloud revenues.” Its failure would hit the whole industry’s finances.
- Inside OpenAI’s Reboot (TIME) and OpenAI’s Big Slowdown: Alex Heath’s reporting from inside OpenAI in the same weeks, on the product and sales reboot that this piece reads as catch-up on the enterprise, a strategy Zitron notes was led by the now-departed Lightcap.
- The AI Hater’s Manifesto (a week later) widens this argument to the whole industry. AI Is Already in Dangerous Hands covers the IPO delay to 2027 that followed.
- Let AI Burn: Zitron’s earlier no-bailout polemic. Here he again declines to “engage with stuff about government bailouts.”
- Dead Money (Ed Zitron) and Where’re All The AI Chips (Ed Zitron): later Zitron pieces, which report that Anthropic’s leaked S-1 shows it spent $2.75 to make $1 in 2025.